International purchasing rarely ends when a supplier seals a carton. A container may cross several ports, change vessels, and wait under harsh weather before reaching its destination. During that journey, Marine Cargo Insurance Coverage can protect buyers from selected physical losses and transport-related risks. Yet many buyers treat insurance as a routine checkbox. That assumption can become expensive.
Coverage depends on the policy wording, declared cargo value, transport route, packing quality, and applicable exclusions. A wet pallet of electronic components may look minor at departure but create serious losses after condensation, delay, or mishandling. Experienced buyers examine more than the premium. They review insured risks, deductibles, claim procedures, documentation requirements, and the responsibilities of carriers and logistics providers. Small details matter.
Read the clauses carefully.
Reliable planning begins before shipment. Buyers should compare reputable insurers, confirm whether coverage applies from warehouse to final destination, and check how partial damage is assessed. Institute Cargo Clauses can provide useful reference points, but policy terms still require careful review. Local insurance practice and commercial contracts may also affect the buyer’s responsibilities.
No policy removes every risk. That is worth remembering. Weak packaging, inaccurate invoices, unclear product descriptions, or late reporting can complicate a valid claim. The following seven coverage tips help global buyers ask better questions, document decisions, and avoid relying on assumptions when valuable cargo is moving across borders.
Understanding Marine Cargo Insurance and Its Role in Global Trade
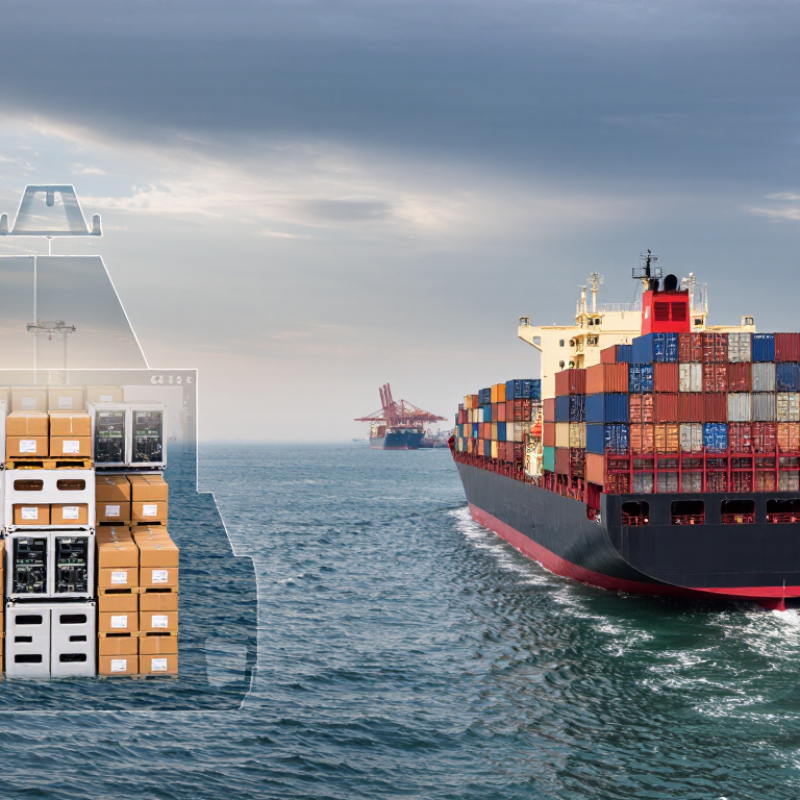
Marine cargo insurance protects goods while they move between sellers, ports, warehouses, and buyers. It transfers certain financial risks, but it does not make every loss recoverable. Coverage depends on the policy wording, declared value, transport route, packaging, and exclusions. A careful buyer checks these details before shipment.
Check whether the policy covers all risks or only named perils. Confirm protection against water damage, theft, handling damage, and accidents. Ask whether delay, temperature changes, or inadequate packaging are excluded. Declare the correct cargo value, including freight and related costs when required. Describe the goods accurately. Vague descriptions can create claim problems. Small details matter.
Review the route and transfer points, including inland legs and temporary storage. Keep invoices, packing lists, photographs, inspection reports, and transport records together. Strong evidence supports a faster assessment. Inspect cartons when they arrive, and record wet pallets, broken seals, or crushed corners immediately. Notify the insurer and carrier within the stated time limit. Do not discard damaged packaging too soon. A surveyor may need it. One practical weakness deserves attention: buyers often insure the cargo but overlook poor packing. Insurance cannot replace proper loading, moisture control, or secure labeling. Policy language should be reviewed with a qualified insurance professional, because coverage terms differ across jurisdictions and shipments.
7 Marine Cargo Insurance Coverage Tips for Global Buyers? - Understanding Marine Cargo Insurance and Its Role in Global Trade
| Tip | Coverage Dimension | What the Buyer Should Check | Relevant Fact or Benchmark | Recommended Action |
|---|---|---|---|---|
| 1Choose the Correct Coverage Level | Institute Cargo Clauses | Confirm whether the policy uses ICC (A), ICC (B), or ICC (C) wording and identify the listed exclusions. | ICC (A) generally provides the broadest “all risks” cover, subject to exclusions. ICC (B) and ICC (C) provide narrower cover for specifically listed risks. | Select coverage according to the cargo’s value, fragility, handling requirements, route, and loss exposure rather than choosing solely by premium. |
| 2Confirm the Insured Value | Sum Insured and Valuation | Check whether the insured amount includes the commercial invoice value, freight, insurance costs, and an agreed margin for incidental expenses or expected profit. | A commonly used marine cargo valuation is 110% of the CIF or CIP value, but the applicable amount must be stated in the policy or certificate. | Request a written valuation formula before shipment and ensure it matches the sales contract and applicable delivery term. |
| 3Verify the Transit Scope | Warehouse-to-Warehouse Protection | Review the exact starting point, destination, transshipment locations, temporary storage provisions, and the time limit for cover after arrival. | Cargo cover may begin when goods leave the initial warehouse and may end when they are delivered to the final warehouse or after a specified period, depending on the wording. | Match the insured journey with the actual logistics route, including inland trucking, port storage, transshipment, and customs delays. |
| 4Review Exclusions and Special Risks | War, Strikes, Delay, and Inherent Vice | Identify exclusions for war, strikes, riots, delay, ordinary wear and tear, inadequate packing, inherent vice, and deliberate acts. | Standard cargo clauses commonly exclude certain war and strike risks, while loss caused solely by delay is generally not covered unless specifically agreed. | Purchase suitable additional clauses or endorsements when the route, commodity, political environment, or storage conditions require them. |
| 5Set a Practical Deductible | Excess or Deductible | Check whether the deductible is a fixed amount, a percentage of the insured value, or a percentage of the loss. | A deductible is the portion of an insured loss that remains payable by the insured; a higher deductible can reduce premium but increases the buyer’s financial exposure. | Compare the deductible with the shipment value, expected loss frequency, cash-flow capacity, and the cost of handling small claims. |
| 6Protect the Claims Position | Evidence and Notification | Establish procedures for inspecting damaged cargo, recording visible damage on transport documents, notifying the carrier, and preserving packaging and evidence. | Policies commonly require prompt notice and reasonable steps to minimize loss; exact notification periods depend on the policy and transport contract. | Keep the policy or certificate, commercial invoice, packing list, bill of lading or waybill, survey report, photographs, delivery records, and claim correspondence. |
| 7Align Insurance with the Sales Contract | Risk Transfer and Incoterms® | Compare the insurance obligation under the agreed Incoterms® rule with the point at which risk transfers from seller to buyer. | Under CIF and CIP, the seller arranges insurance under the applicable rule, but the buyer should still verify the coverage, insured value, destination, and claims procedure. | Obtain the insurance certificate before or at shipment and confirm that the named insured, voyage, cargo description, value, and destination are accurate. |
FAQS
It protects goods during movement between sellers, ports, warehouses, and buyers. Coverage transfers certain financial risks. It does not cover every loss.
Check the policy type, exclusions, declared value, route, and transfer points. Confirm protection for water damage, theft, handling damage, and accidents. Small wording changes matter.
Named-perils coverage protects against listed events only. Broader coverage still has exclusions. Poor packing, delay, or temperature damage may remain uncovered.
Include the invoice value, freight charges, duties, and a reasonable margin. Underinsuring a valuable container can create a serious claim shortfall. Do not assume carrier liability equals cargo value.
A higher deductible may lower the premium. However, your company must pay more after a loss. Check whether it applies per shipment, container, or incident.
Often, it does not. Insurance cannot replace secure loading, moisture control, or clear labeling. This is a common oversight. The packaging may be the weak point.
Keep invoices, packing lists, transport records, photographs, inspection reports, and delivery receipts. Photograph wet pallets, broken seals, and crushed corners. A missing seal number can weaken an otherwise credible claim.
Inspect the cartons immediately and record visible damage. Notify the insurer and carrier within the required time limit. Keep the damaged packaging. A surveyor may need it.
Yes. Review inland transport, transshipment, temporary storage, and final delivery. Warehouse-to-warehouse wording may not cover extended storage. Coverage can become unclear between handoffs.
Terms differ across jurisdictions, goods, routes, and handling conditions. A qualified insurance professional can compare the wording with your actual shipment. Verbal assurances are not enough. The policy controls.
Conclusion
Marine Cargo Insurance Coverage is an essential tool for global buyers seeking to protect goods as they move through complex international supply chains. Before selecting a policy, buyers should assess shipment value, cargo type, packaging quality, route conditions, weather exposure, handling risks, and the reliability of transport partners. This evaluation helps determine suitable coverage limits, deductibles, transit terms, and policy types for different stages of transportation.
Buyers should also review exclusions, warranties, documentation requirements, and the responsibilities of carriers and other logistics providers. Clear records, including invoices, packing lists, transport documents, inspection reports, and photographs, can support an efficient claim if cargo is lost or damaged. By matching insurance protection to actual shipment risks and understanding the claims process in advance, global buyers can reduce financial uncertainty, improve supply chain resilience, and respond more effectively to unexpected transportation incidents.